Debt
Kakeibo when you are paying off debt
A repayment plan and a household ledger answer two different questions, and most people paying down a balance are only running one of them. Here is where the payments actually sit, and what the ledger is genuinely for while they last.
- Published
- 15 September 2026
- Written by
- The Kakeibo Method team
- Reading
- 9 minutes
- Filed under
- When the month is difficult
Kakeibo works while you are paying down a balance, with two placements settled up front: the minimum payment is a fixed cost and sits in Survival, and anything you pay above the minimum sits with the savings promise, moved before the month is planned. The ledger does not build a repayment plan. It tells you what the plan can have.
Two things this page is not. It is not advice about which balance to clear first or whether to save before repaying: those depend on rates, on how secure your income is and on your own circumstances, and we publish a budgeting ledger rather than any kind of counsel. And it is not the low income guide. If Survival plus the minimum payments takes almost everything that arrives, the useful page is kakeibo on a low income, which is written for a month with nothing left to trim. This one assumes the month has some room in it and a claim on the months ahead.
The two placements, and why they are different
A minimum payment is not a decision. It is an obligation with a date on it, it arrives whether or not you thought about it, and missing it has consequences that have nothing to do with budgeting. That is precisely the definition of Survival, and treating it as anything else produces a plan that looks like it has money in it and does not. Put the minimums in Survival next to the rent and stop thinking about them.
Anything above the minimum is the opposite kind of thing. It is money you could have spent and chose not to, which is the same shape as a savings promise even though the money is going out rather than in. So it belongs where the promise belongs: off the top, before the four envelopes are filled, moved on payday rather than found at the end of the month. The order is the argument. A payment decided last is competing against every purchase that came before it, and a payment moved first is competing against nothing.
The question a ledger answers that a repayment calculator cannot
Repayment calculators are good at one thing and completely silent about another. Give one a balance, a rate and a monthly payment and it will tell you when the balance reaches zero. What it cannot tell you is whether that monthly payment is a figure your household can actually survive, month after month, without the shortfall reappearing on a card in week three. That is not an arithmetic question. It is a question about what your months really contain, and a ledger is the only thing that answers it.
This is why the order in practice runs ledger, then plan. Record one honest month first, with no attempt to improve anything, and read what Survival, Optional, Culture and Extra actually came to. The figure you can commit to repayment is whatever survives that reading, and it is almost always different from the number a household would have guessed. Work the monthly figure out from your own totals rather than from a borrowed percentage: the reasoning is the same as in how much should you save each month, with the promise pointed at a balance instead of at a savings account.
The four envelopes while a balance is coming down
- Survival. Rent, utilities, food, transport, and every minimum payment. This is the envelope that decides whether the plan is real, and it is worth rebuilding from three months of actual spending rather than from what you believe it costs.
- Optional. Where the repayment money is usually found, and the envelope most likely to be cut to nothing in a burst of enthusiasm in month one. A figure you can hold for a year beats a figure you can hold for three weeks.
- Culture. The one households delete first while repaying, and the deletion is why so many repayment plans last two months. Spending on being a person is not an indulgence tax, and a plan with no room in it at all is a plan that gets abandoned rather than completed.
- Extra. Keep it funded, even at a small figure. The unplanned repair is the single most common way a repayment plan gets undone, because a household with nothing set aside meets it with the same card it is trying to clear. A funded Extra is not a distraction from the balance. It is what protects the balance.
The buffer question, stated rather than answered
Whether to hold savings while carrying a balance is genuinely disputed, and anyone who tells you it is obvious is skipping the part where it depends on your rates, your job and what happens if the car fails next week. The case for a buffer is the one in the paragraph above: without it, the next ordinary emergency goes back onto the debt and the plan restarts. The case against is that money sitting still while interest accrues is costing you. Both are real. We are not going to pick for you, and a page that did would be pretending to a relationship with your finances that it does not have.
What the ledger contributes is the size of the question. If Extra has been costing you a certain amount a month across a year of real records, you know roughly what the unexpected actually costs your household, which turns the buffer argument from a principle into a number. Free, non commercial debt advice services exist in most countries and are worth using before any commercial offer, particularly if payments are being missed. That is a better door than any budgeting site, this one included.
Cards, while you are clearing cards
The recording rule does not change and it is worth restating because it gets muddled exactly here. Enter a purchase on the day you decide to make it, in the envelope it belongs to, whatever payment method is involved. The card payment itself is not a new expense: it is the settlement of purchases already recorded, and entering it again would double count your own month. The full treatment of cards, subscriptions, buy now pay later and the lag between the decision and the money is in kakeibo with a credit card.
One practical note for a household repaying a card it still uses. Keeping the ledger honest is harder when the balance is both the problem and the payment method, and the safe to spend figure becomes more useful than the statement, because the statement is describing last month. The safe to spend calculator runs that sum on whatever figures you give it.
The monthly reckoning while repaying
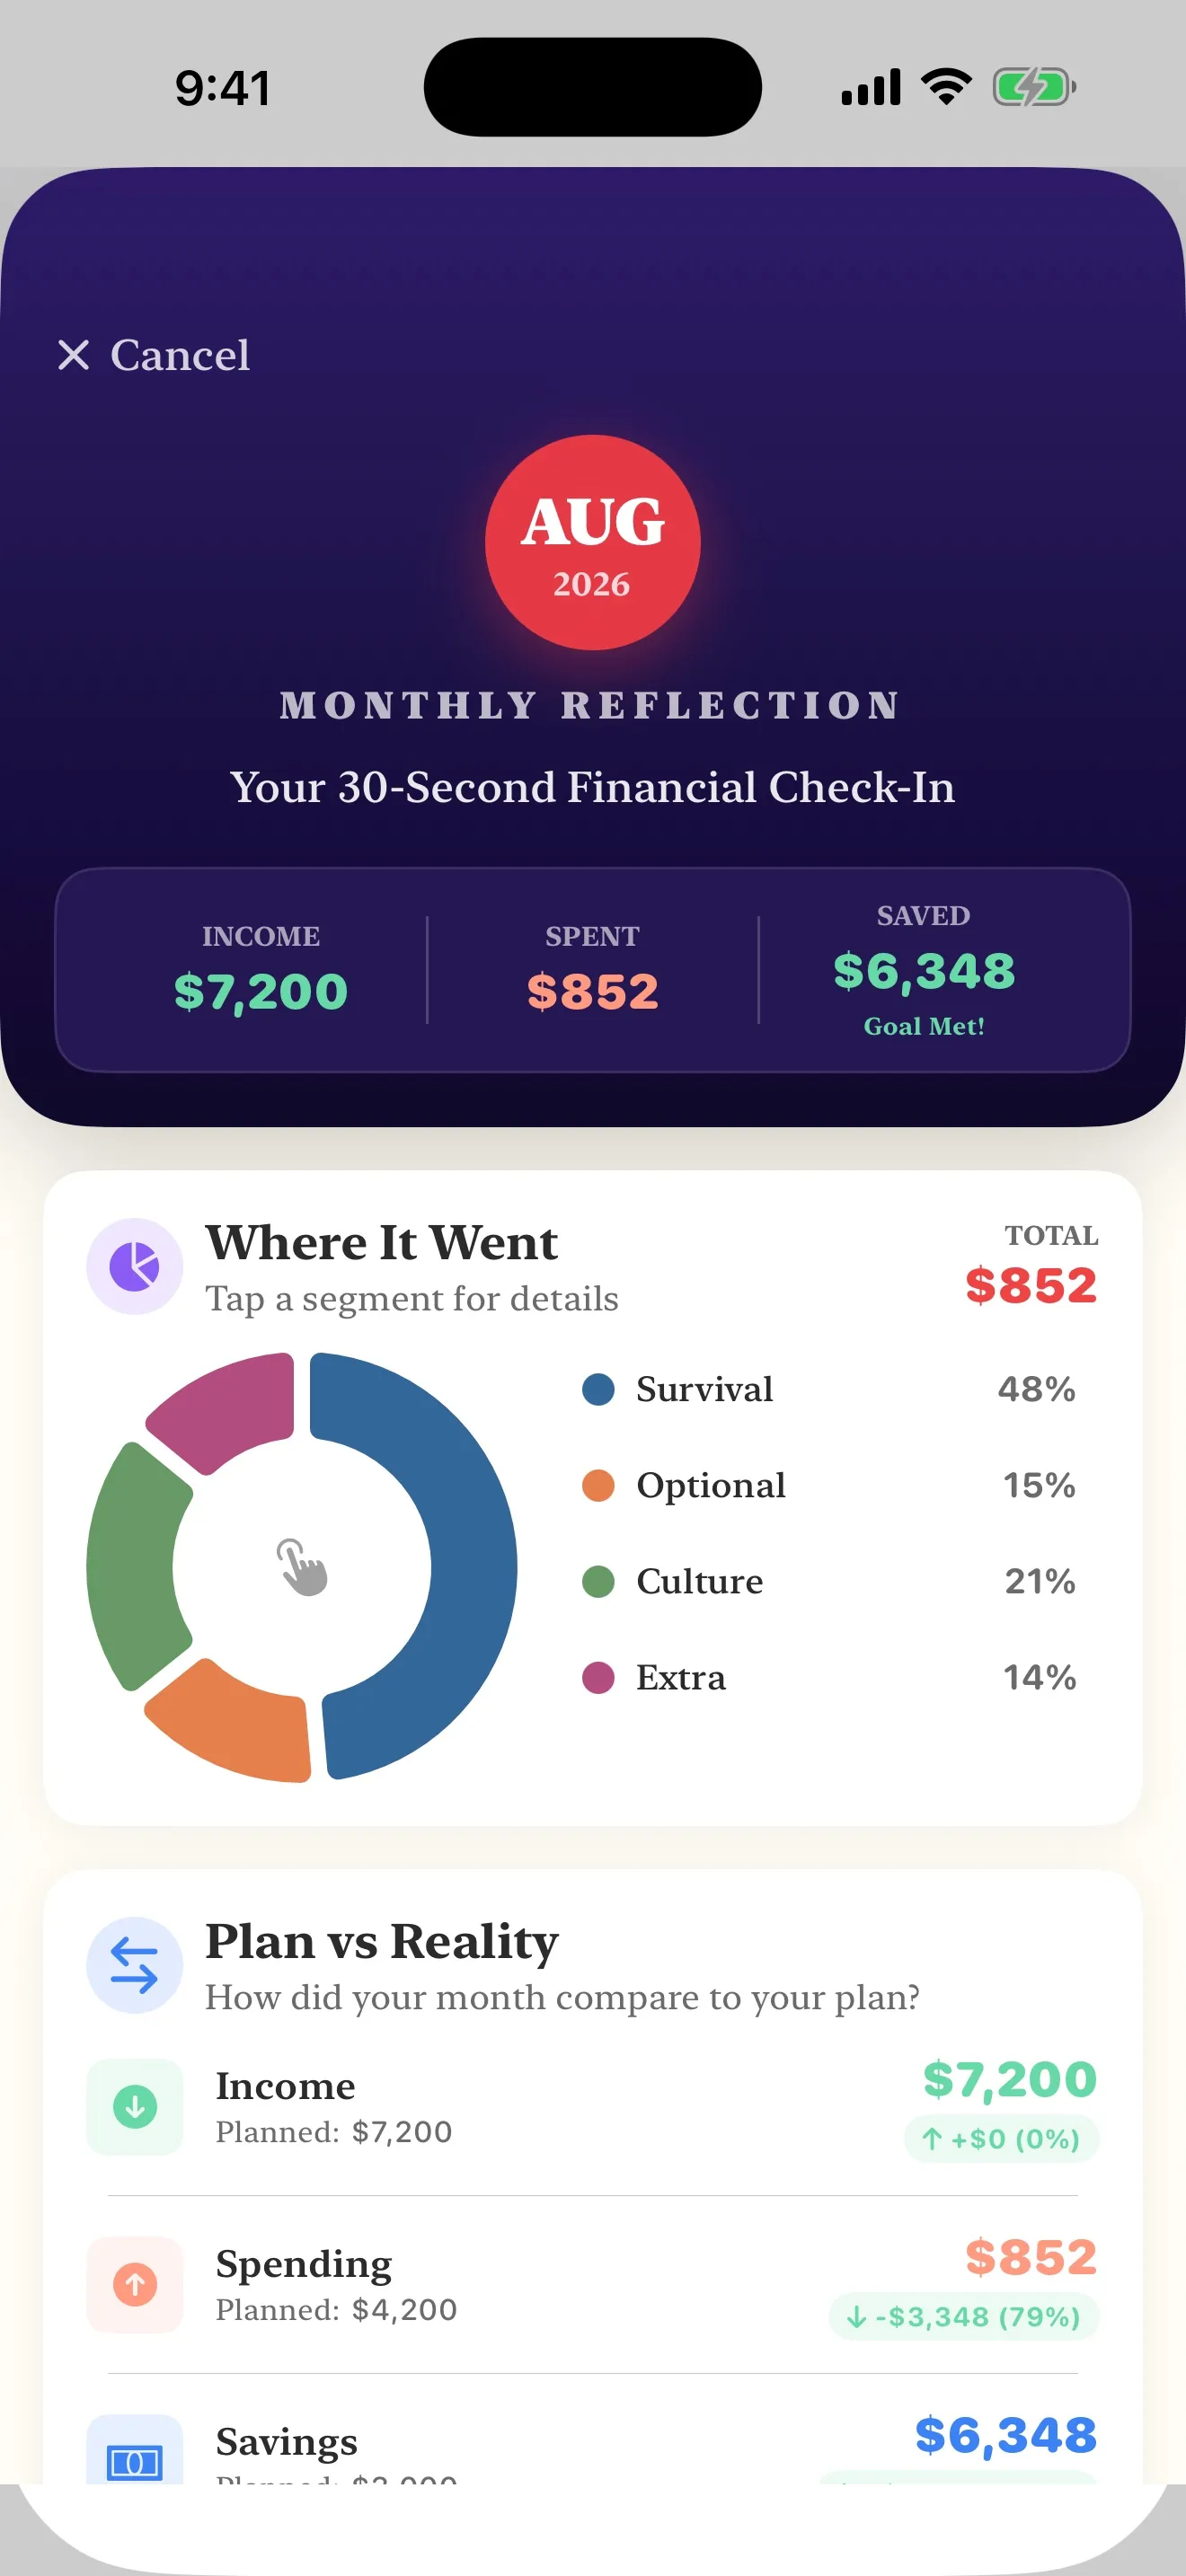
The reflection matters more here than in an ordinary month, for a reason that is not obvious: a repayment is slow, it is mostly invisible, and a household that cannot see progress stops making it. The monthly sitting is where the balance gets written down next to the month it came out of, which is the only place the two ever meet.
The four questionsAnswered in writing
- 01How much money do you have?Everything arriving this month, counted before anything is committed.
- 02How much would you like to save?Decided now and moved out first, before a single envelope is filled.
- 03How much are you spending?Recorded by hand, in four envelopes, at the moment of spending.
- 04How can you improve?Answered at the end, in sentences, against the numbers rather than a feeling.
Add one line to the reckoning that the standard four do not ask for: what the balance was at the start of the month and what it is now. Written down, in your own hand, every month. It is the single most motivating number in a repayment and almost nobody records it, because the statement shows it once and then it scrolls away. The longer prompts for the sitting are in the four questions guide.
When the ledger says the plan does not fit
Sometimes an honest month produces an answer nobody wants: Survival plus the minimums is everything that arrives, and there is no figure left to commit. That is a real finding rather than a failure of the method, and it is worth more than a plan built on a number that was never there. What follows from it is not a budgeting change, because the gap is between income and fixed costs and no ledger closes that by describing it.
Two things are still true in that situation. The number is worth having before the month starts rather than after it, which is the honest case for the method made in full in kakeibo on a low income. And a month that goes wrong in the middle is recoverable without abandoning the record, which is set out in what to do when you blow the budget. Neither page promises anything. Both are about seeing the shape of it early enough to act.
Common questions
- Where do debt payments go in kakeibo?
- In two places, and the split is the whole trick. The minimum payment is a fixed obligation that behaves exactly like rent, so it sits in Survival. Anything you pay above the minimum is a choice you are making with money you could have spent, so it belongs with the savings promise and comes off the top before the four envelopes are filled.
- Should I save or pay off debt first?
- That is a genuine trade off rather than a settled question, and the answer depends on the interest you are paying, on how secure your income is, and on what happens to your household if something breaks next week. We are a budgeting site rather than an adviser and we are not going to decide it for you. What the ledger contributes is the figure the decision needs: what is actually available each month once Survival is paid.
- Does kakeibo work when most of the month is already committed?
- It works, but be clear about what it is doing. With little discretion left, the value is not in trimming, it is in knowing the number before the month starts and in seeing a balance move against a plan rather than against a hope. If Survival plus the minimums is close to everything that arrives, read our guide on kakeibo with a low income, because that is a different problem.
- Should I keep an emergency buffer while paying down a balance?
- Most budgeting traditions say some buffer is worth holding, on the argument that a household with nothing set aside meets the next unexpected repair by borrowing again. How large that buffer should be is disputed and depends on your circumstances. In kakeibo terms it is the Extra envelope, and the practical point is that a funded Extra is what stops a repayment plan being undone by an ordinary Tuesday.
- What about credit cards while I am repaying?
- The recording rule is the same as always: enter the purchase on the day you make the decision, not on the day the statement clears, because the decision is the thing the method is trying to catch. The card payment itself is not a new expense, it is the settlement of purchases you already recorded. We have a fuller guide on cards, subscriptions and the lag between the decision and the money.
- Is kakeibo a debt payoff method?
- No, and it is worth being plain about that. It has no repayment schedule, no interest arithmetic and no opinion about which balance to clear first. It is a ledger: it tells you what the month actually contains, which is the input a repayment plan needs and the one most households do not have.
Read nextThe whole library →
Where this one leads
Survival takes most of itKakeibo on a low incomeWhen there is nothing left to trim, the value is knowing the number before the month starts.8 min readYou want a number, not a percentageHow much to saveNo agency publishes a recommended rate. Work the figure from your own income and your own Survival costs instead.9 min readThe month is already over budgetWhen you blow the budgetRe-plan the rest of the month from what is genuinely left, rather than closing the book until the first.8 min read
One honest month, then the plan
A repayment schedule needs a figure your household can actually hold. Record a month without changing anything, read the four envelopes back, and build the plan on what was really there.
Get the Kakeibo app freeiPhone and iPad · Free tier, no account needed